What is the Warm Homes Loan Scheme?
The Warm Homes Loan Scheme helps eligible UK property owners spread the cost of qualifying energy upgrades through participating lenders. EPC now offers Zopa Warm Homes Loan finance for eligible heat pumps, solar panels and battery storage. It is a loan that you repay, not a grant or free installation. The government factsheet explains the national scheme; EPC’s current repayment options are set out below.
For a homeowner replacing a gas or oil boiler or considering solar, the useful starting point is the upgrade needed now, a suitable design and a clear installation price. You do not have to buy a heat pump, solar panels and a battery together. Finance can change when you pay the cost; it does not remove the need to check likely running costs or whether repayments are manageable.
Who may be eligible for a Warm Homes Loan?
The government’s basic eligibility rules cover owners of residential properties in the UK, whether or not they have a mortgage. Lenders can set additional conditions and carry out credit and affordability checks. Meeting the property rules does not guarantee a loan.
EPC can arrange Zopa Warm Homes Loan finance for eligible heat-pump, solar and battery installations. We will assess your proposed installation and identify the eligible work in your quotation. Zopa carries out the credit and affordability checks and makes the lending decision.
If you are on a lower income, check whether grant-funded support may be available before committing to borrowing. The government’s loan overview points readers towards relevant grant routes. The similarly named Warm Homes: Local Grant is a different programme with its own eligibility and delivery arrangements.
Can the loan pay for heat pumps, solar panels and batteries?
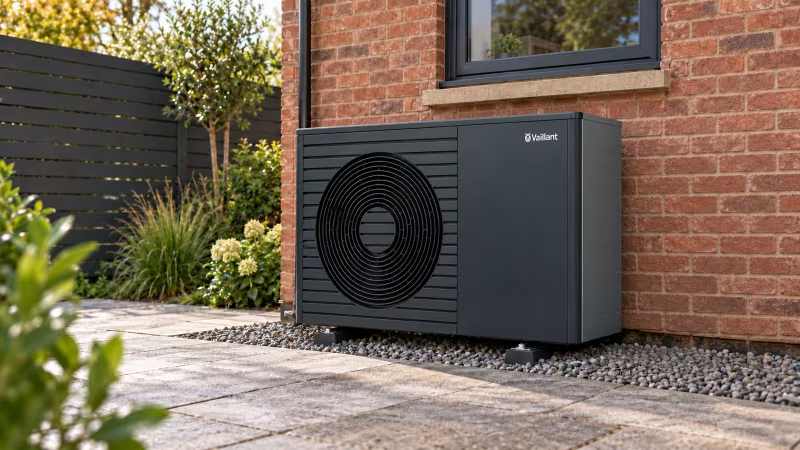
EPC offers Zopa Warm Homes Loan finance for eligible heat pumps, solar panels and battery storage, including suitable combinations. Your quotation will identify the costs and repayment terms that apply to each part of the project. Scheme eligibility rules still apply, including the exclusion for replacing an existing low-carbon heating system with another heat pump.
| Technology | Published scheme ceiling |
|---|---|
| Solar photovoltaic panels | Up to £15,000 |
| Electrical battery storage | Up to £15,000 |
| Air-to-water heat pump | Up to £20,000 before any BUS grant deduction |
| Ground-source heat pump | Up to £35,000 before any BUS grant deduction |
These are scheme limits, not installation prices or guaranteed borrowing amounts.
The detailed scheme rules set the limits and eligible costs. For heat pumps, do not add the full published ceiling to a BUS grant: the grant is deducted when calculating the eligible loan amount. Your quotation, any other funding and the lender’s assessment determine what can actually be financed.
For a heat-pump installation, establish the heating design and any necessary changes to the home. For solar panels and battery storage, consider the roof, electricity use and proposed system together. Ask for the quotation to identify eligible installation work and any separate costs you will need to cover.
Can I combine a Warm Homes Loan with a Boiler Upgrade Scheme grant?
Yes, where both sets of rules are met. The Warm Homes Loan Scheme rules specifically permit a loan alongside the Boiler Upgrade Scheme (BUS) to finance the eligible remaining cost. A grant reduces the cost you need to meet; the loan spreads repayment of the approved balance. The same cost must not be funded twice.
BUS supports qualifying properties in England and Wales. The standard grant for an eligible air-to-water or ground-source heat pump is £7,500. A temporary total grant of £9,000 is available for qualifying oil or LPG replacements at properties without a mains-gas connection. The uplift requires a properly made application in the relevant window ending 31 March 2027; owner consent, identity checks and other requirements matter. Read Ofgem’s property-owner guidance for the conditions. Booking an installation does not secure that grant.
Tell the installer and lender about all proposed funding, including any other contribution you expect. Ask them to confirm that it can be combined and how it affects the financed balance. A mortgage-provider contribution, for example, should not be treated as money available until its conditions are met.
Which Warm Homes Loan finance options does EPC offer?
EPC’s Zopa Warm Homes Loan options are available now. Choose from the repayment periods below for eligible installations. The options differ between heat pumps and solar or battery projects.
| Installation | Interest-free at 0% APR | Interest-bearing at 3.6% APR |
|---|---|---|
| Heat pump | 36 or 60 months | 120 months (10 years) |
| Solar panels and/or battery storage | 36 months | 120 months (10 years) |
Finance is subject to eligible work, status and Zopa’s credit and affordability checks. EPC Improvements Ltd is a credit broker, not a lender.
For a combined installation, EPC will explain which costs and terms apply to each part. The 60-month interest-free heat-pump option does not extend automatically to solar or battery costs. Your quotation and credit agreement show the deposit, monthly payments and total amount payable for your project.
When comparing an offer, look at the whole agreement:
Amount borrowed and deposit: confirm the cash price, approved grant deduction, your contribution and the balance financed.
APR and charges: check the annual percentage rate, interest rate, fees and any conditions attached to an introductory offer.
Repayment period: a smaller monthly payment over a longer term may mean a greater total repayment.
Total amount repayable: compare the full cost, not just the first monthly figure.
Security and flexibility: establish whether the borrowing is secured against your home, and check early-repayment, missed-payment and moving-home terms. If borrowing is secured on your home, missing repayments could put your home at risk.
Keep projected energy savings separate from the loan repayment. Bills depend on the property, system design, use and tariffs; savings may not match or exceed the finance payments. Use realistic estimates for the installation and repayments you can afford alongside your other commitments.
How do I apply for a Warm Homes Loan through EPC?
You can apply for Zopa Warm Homes Loan finance through EPC as part of your eligible installation. Start with an enquiry: EPC will assess the proposed work, prepare your quotation and talk you through the payment options before sending a proposal to review. Zopa makes the lending decision. An installation proposal and a credit agreement are separate documents. See EPC’s finance options and application process.
Discuss the upgrade you need. Tell EPC whether your priority is replacing a gas or oil boiler, installing solar panels, adding a battery or considering a combination. Gather your energy-use information and explain any urgent heating needs.
Agree a suitable design and quotation. EPC will assess the proposed work and set out the installation price. Identify any applicable grant, your proposed deposit, eligible installation costs and separately priced extras.
Review the payment options. EPC can talk you through the proposed term, monthly repayments and total amount repayable using the applicable product information. Compare the complete cost with paying upfront. An illustration is not a loan approval.
Review the installation proposal. EPC will send a proposal for you to review. Before signing, check the scope, deposit, cancellation terms and what happens if finance is declined. Signing an installation proposal does not approve a loan.
Complete the finance application. EPC will explain the Zopa application process. Zopa assesses your application and makes the lending decision. Read the credit agreement, including the repayment schedule and total amount payable, before accepting it.
Confirm the installation arrangements. Agree funding, payment dates and the installation timetable before relying on finance to proceed. Keep the quotation, proposal, credit agreement, invoices and relevant certification.
If you are replacing a gas or oil boiler, EPC can help you compare the heat-pump installation you need now with an option that includes suitable solar panels or battery storage. Compare the installation price, amount borrowed and total repayment as well as the monthly payment. You can also plan for later upgrades without installing everything at once.
Common questions about Warm Homes Loans
Is the Warm Homes Loan Scheme the same as the Boiler Upgrade Scheme?
No. A Warm Homes Loan is repayable finance from a participating lender. BUS is a grant for qualifying heating installations in England and Wales. They can work together for eligible costs, but each has separate conditions.
Can I use a Warm Homes Loan for solar panels and a battery without a heat pump?
Yes. EPC offers Zopa Warm Homes Loan finance for eligible solar panels and battery storage without requiring a heat pump. Choose 36 months interest-free at 0% APR or 120 months at 3.6% APR, subject to eligible work, status and Zopa’s credit and affordability checks. Zopa assesses each application and makes the lending decision.
Do I have to improve my whole home at once?
No. The national eligibility guidance allows one or more qualifying improvements. Plan the system around your home and budget, and confirm the lender’s minimum borrowing amount and other product conditions.
Does 31 March 2027 mean the Warm Homes Loan Scheme is ending?
No. Zopa Warm Homes Loan finance is available through EPC. The 31 March 2027 date discussed here is the closing date for the temporary BUS oil/LPG uplift application window; it is not a stated end date for the whole loan scheme. EPC can help you plan against the separate grant requirements and installation timetable. Finance remains subject to eligibility, credit and affordability checks.
Can EPC help me choose the work and explain the next steps?
Yes. Zopa Warm Homes Loan finance is now available through EPC for eligible installations. EPC can assess your proposed work, prepare a quotation, explain payment options and send a proposal for you to review. Zopa makes the lending decision, subject to its eligibility, credit and affordability checks. EPC Improvements Ltd is a credit broker, not a lender, and does not provide financial advice.
Sources and further reading
Sources checked 18 November 2026. Scheme rules, availability, lender terms and tax treatment can change; confirm the current position before committing.
- GOV.UK — Warm Homes Loan Scheme factsheet
- GOV.UK — scheme eligibility
- DESNZ — detailed scheme rules, September 2026 (PDF)
- GOV.UK — how to apply
- GOV.UK — participating lenders
- Ofgem — BUS guidance for property owners, version 5.2 (PDF)
- MoneyHelper — personal loans and comparing borrowing costs
- Citizens Advice — mortgages and secured loans